Recession vs. Depression: What’s the Difference?
Recession vs. depression: both words describe an economy in trouble. One shows up every few years. The other has happened once in the last century.
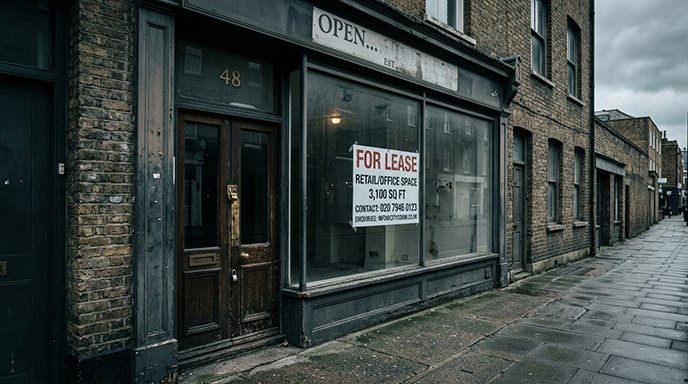
Recession vs. depression: recessions are a normal part of the cycle
So what actually separates a recession vs depression? Start with the more common one. A recession is a significant, broad decline in economic activity that lasts more than a few months. In the United States, the National Bureau of Economic Research officially declares recessions after the fact. It looks at GDP, employment, income, and industrial production together, rather than relying on any single number.
Recessions happen regularly. Since World War II, the U.S. has gone through about a dozen recessions, roughly one every six to seven years. The actual gaps vary widely. Some are short and mild. The COVID-19 recession in 2020 lasted just two months. Others drag on longer and cut deeper, like the 18-month recession from December 2007 to June 2009. The housing market’s collapse, and the financial crisis that followed, drove that one.
Recession vs. depression: what actually makes them different
There’s no official, universally agreed-upon definition of an economic depression the way there is for a recession. In practice, economists use the term for a downturn that’s dramatically longer and more severe than a typical recession. That usually means a GDP decline of 10% or more. It also means unemployment rates well above what’s considered normal, and a recovery that takes years rather than months.
The Great Depression, which ran from 1929 to roughly 1939 in the United States, is the reference point everyone uses. At its worst, in 1933, unemployment reached about 25%. GDP fell by roughly a third from its pre-crash level. Thousands of banks failed, wiping out people’s savings since deposit insurance didn’t exist yet. It took the better part of a decade before the economy fully recovered. The massive government spending tied to World War II ultimately made the difference.
By comparison, even the worst recessions of the past century, including 2008, look mild. Unemployment during the 2008 financial crisis peaked at about 10%. Bad, but nowhere close to Depression-era numbers.
Why we haven’t had another depression since
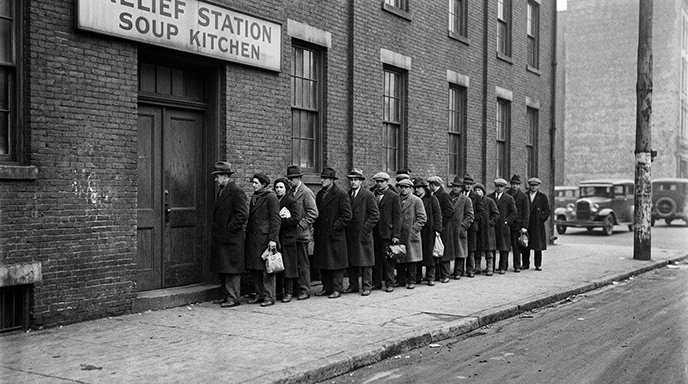
Part of the reason the Great Depression hasn’t repeated is that it fundamentally changed how governments respond to economic crises. The government created the Federal Deposit Insurance Corporation in 1933. It was built to prevent the kind of bank runs that wiped out savings during the Depression. The Federal Reserve has also become much more aggressive about intervening early in a downturn. It cuts interest rates and injects liquidity into the financial system. Those are lessons drawn directly from the mistakes of the early 1930s. Back then, the Fed actually tightened the money supply and made things worse.
You can see this playbook in action during the 2008 crisis. The Fed cut interest rates to near zero and bought large amounts of financial assets to keep credit flowing. That approach became known as quantitative easing. The government also passed the Troubled Asset Relief Program to stabilize banks directly. None of that existed as a policy tool in 1929. Whether or not those interventions worked well is debatable. But they represent a fundamentally different, faster, more coordinated response. It’s nothing like what happened the last time the economy fell this hard.
What a recession actually feels like
For most people, a recession shows up as some combination of layoffs and hiring freezes. It also shows up as falling home and stock values, and tighter credit. Companies pull back on spending when demand slows, which often means job cuts. Banks tend to tighten lending standards during a downturn, making it harder to qualify for a loan or a mortgage. That happens right when people might need one most. Retirement accounts tied to the stock market can lose a meaningful chunk of their value in a matter of months. Even so, they often recover over the following years.
This is part of why financial advisors so consistently recommend building an emergency fund before a downturn hits, not during one. Once a recession is underway, income becomes less predictable and credit becomes harder to access. That happens right when you might need a financial cushion the most.
How recessions end
Recessions typically end when some combination of lower interest rates, reduced debt burdens, and pent-up demand starts pulling spending back up. As the Federal Reserve cuts rates, borrowing gets cheaper. That encourages businesses to invest and consumers to make bigger purchases, like homes and cars. Businesses eventually sell off the inventories that built up during the slowdown. That prompts them to ramp production back up and rehire.
There’s no fixed timeline. Some recessions resolve in a matter of months once the underlying shock passes, as with COVID-19. Others, especially ones tied to a financial crisis where banks are also impaired, tend to drag out longer. Credit stays tight even after rates come down, since banks themselves are working through bad loans on their own books.
If a downturn does hit, a cash cushion sized to your actual monthly expenses matters more than trying to predict how long it will last. Our Emergency Fund Calculator can help you figure out a reasonable target based on your own expenses.
Common questions about recessions and depressions
Since World War II, U.S. recessions have lasted anywhere from two months (the 2020 COVID-19 recession) to 18 months (2007-2009). Most fall somewhere in the 8-to-12-month range. The National Bureau of Economic Research determines the exact start and end dates after the fact, once enough data is available.
A few things fed into the crash’s severity: speculative buying on borrowed money, an overheated stock market, and a fragile, poorly regulated banking system. That combination helped turn it into the depression that followed. There was no deposit insurance at the time. When banks failed, depositors simply lost their savings, deepening the crisis.
In the United States, the National Bureau of Economic Research’s Business Cycle Dating Committee makes this determination. It looks at a range of indicators, employment, industrial production, real income, and GDP, rather than relying on any single statistic. Because the committee waits for reliable data, it typically confirms a recession only after it has already begun.
No industry is completely immune to a downturn. But sectors providing essentials, healthcare, utilities, groceries, tend to hold up better than discretionary categories like travel, luxury goods, and entertainment. Demand for necessities doesn’t disappear, even when household budgets tighten.
The U.S. has experienced roughly a dozen recessions since World War II, according to the National Bureau of Economic Research. They’ve occurred on average every 5-7 years, though the actual spacing has varied considerably.
The Great Depression stemmed from a combination of factors. The 1929 stock market crash, fueled by speculative buying on margin, was one. Widespread bank failures with no deposit insurance were another. So was contractionary monetary policy that worsened the downturn.
In theory yes, though no U.S. recession has escalated into a depression since the 1930s. Modern tools like deposit insurance, more active central bank intervention, and automatic fiscal stabilizers have historically helped prevent that escalation.
Historians generally date the Great Depression from 1929 to the late 1930s, roughly a decade. Still, the U.S. economy didn’t fully recover to pre-Depression employment levels until the buildup to World War II.
Discretionary spending sectors like travel, entertainment, and luxury retail tend to take the hardest hit, along with housing and construction. Essential sectors like healthcare, utilities, and groceries typically hold up better during downturns.