What Is an ETF (and How It Differs From a Stock)
An ETF vs stock comparison sounds simple until you actually try to explain the difference out loud. Both trade on an exchange. Both show up as a single ticker symbol in your brokerage account. But one represents a single company, and the other represents a basket of them.
ETF vs Stock: What Each One Actually Represents
A stock represents ownership in one specific company. Buy a share of a single business, and your fortunes rise and fall with that business alone. A strong earnings report can send it up. A scandal or a bad quarter can send it down. Nothing else cushions the swing.
An ETF, short for exchange-traded fund, works differently. It represents ownership in a basket of assets, often dozens or hundreds of stocks, bundled into a single fund. Buy one share of an ETF, and you own a small slice of everything inside it. A weak quarter from one company inside that basket barely moves the total. The loss gets spread across so many holdings at once.
How They Trade the Same Way
Here’s where the confusion starts. ETFs trade exactly like stocks. You can buy or sell shares any time the market is open. Prices move throughout the day based on supply and demand. You can place limit orders, stop losses, and other order types you’d use on any regular stock.
This is actually the whole reason ETFs got created in the first place. Traditional mutual funds only price once a day, after the market closes. Investors wanted the diversification of a fund with the flexibility of a stock. ETFs solved that by wrapping fund-like diversification inside a stock-like trading structure.
Diversification: The Real Difference
The core trade-off in an ETF vs stock decision comes down to concentration versus diversification. A single stock carries company-specific risk. If that one company fails, your investment in it can go to zero. An ETF spreads that risk across many companies, so one failure barely dents your total return.
This spread also caps your upside, though. If you own a single stock that triples in value, your investment triples too. Own that same company inside a broad ETF alongside hundreds of others, and its triple gets averaged down by everything else in the basket that didn’t move nearly as much.
Costs: What You’re Actually Paying
Buying a single stock costs you nothing beyond the trade itself. Most brokerages now offer commission-free trading. An ETF carries an additional cost: an expense ratio. This is a small annual fee baked into the fund’s price. It covers the cost of managing and rebalancing the basket. Most broad-market ETFs charge under 0.10% a year. On a $10,000 investment, that works out to $10 or less annually.
That fee is small, but it’s not zero, and it applies every year you hold the fund. A single stock, by contrast, has no ongoing fee at all. You’re only paying for diversification, not avoiding cost entirely.
A Concrete Example
Say you’re deciding between buying $2,000 of a single tech company’s stock or $2,000 of a broad market ETF. That ETF holds 500 companies, including that same tech company as a small piece of the total. If that one company doubles over the next year, the single-stock position doubles to $4,000. The ETF position only rises by a fraction of that. That same company might make up 5% of the fund, and 495 other companies are also influencing the fund’s price.
Now flip the scenario. That same company drops 50% instead. The single-stock position loses half its value, down to $1,000. An ETF barely notices a drop like that. Dilution across the rest of the basket absorbs most of the impact. Neither outcome is inherently better. It depends entirely on how much risk you’re comfortable carrying in exchange for potential reward.
ETF vs Mutual Fund: A Related but Different Question
People often confuse this comparison with a separate one: ETFs versus mutual funds. Both can track the same index and hold nearly identical assets. The real difference sits in how they trade and price, not what they own. Our article on index funds vs mutual funds walks through that distinction in more depth, including how expense ratios and management style factor in.
For the ETF vs stock question specifically, though, the comparison is more fundamental. It’s not about fund structure. It’s about whether you’re buying one company or many at once.
Dividends Work a Bit Differently
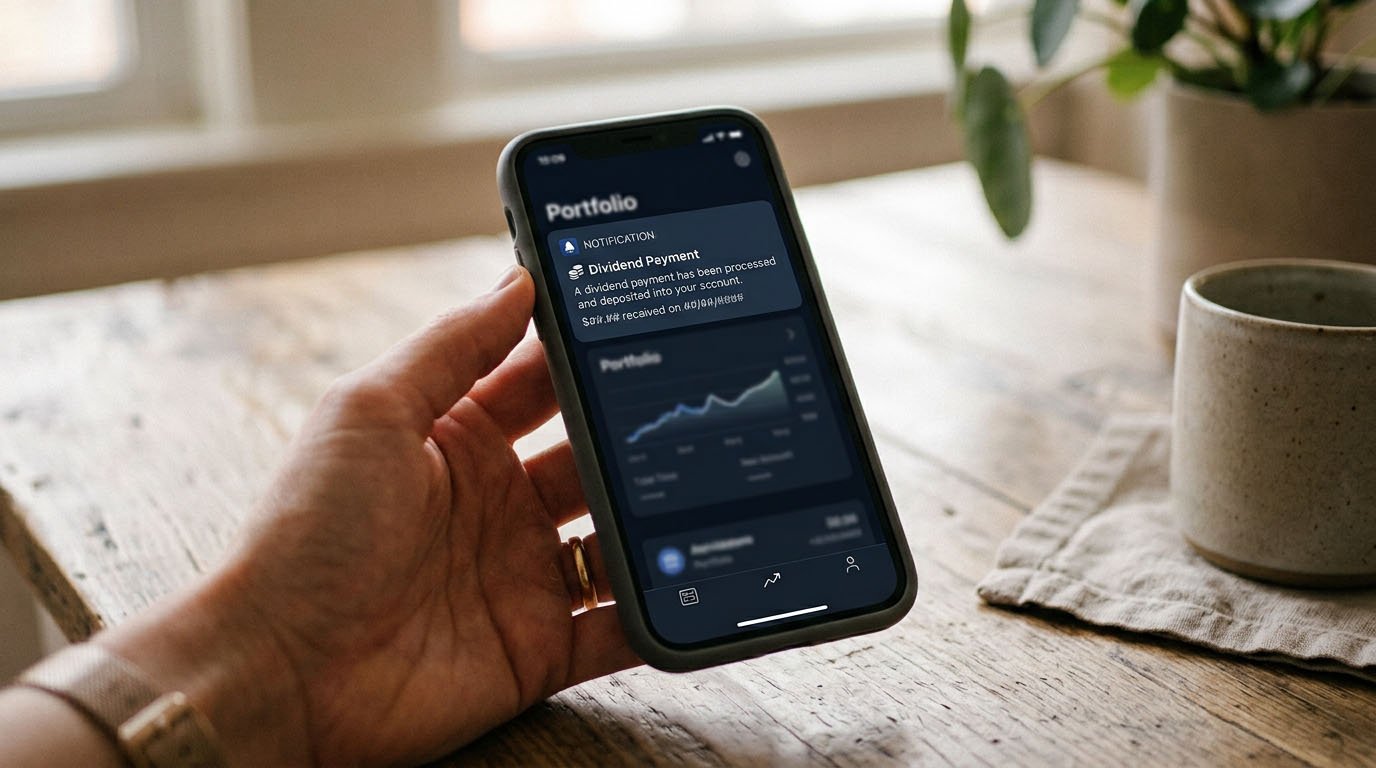
A stock that pays a dividend sends that payment directly to you. It’s based on the company’s own dividend policy. An ETF that holds dividend-paying stocks works differently. The fund collects those payments from every underlying company, then distributes them to ETF shareholders, usually quarterly, combined into a single payment. The mechanics work the same way in practice, but the timing and consistency can differ slightly depending on the underlying holdings.
Reinvesting dividends automatically works for both. Most brokerages let you set up automatic dividend reinvestment for individual stocks and ETFs alike. This quietly compounds your position over time without requiring you to do anything manually.
Which One Should You Actually Own?
Neither option is universally better. A single stock makes sense if you’ve researched a company thoroughly and you’re comfortable with the added risk of concentration. An ETF makes sense as a core holding, giving you broad market exposure without needing to pick winners, and without one bad quarter from a single company wiping out a meaningful chunk of your portfolio.
Many investors use both. They build a core position in broad ETFs, then add individual stocks around the edges for companies they specifically believe in. If you want to see how a given return rate plays out over time regardless of which you choose, our Investment Calculator can project growth based on your own contribution amount and timeline. And if you’re wondering whether investing a fixed amount regularly, rather than all at once, changes your outcome, our guide on dollar-cost averaging covers that separately.
Common questions about ETF vs stock
Generally, yes, in the sense that it spreads risk across many companies instead of concentrating it in one. An ETF can still lose value if the overall market or sector it tracks declines, so it isn’t risk-free, just more diversified.
It’s far less likely, since a broad ETF would need every holding inside it to fail simultaneously, which almost never happens with a diversified fund. A single stock can drop to zero if that one company fails.
Yes, if the ETF holds dividend-paying stocks. The fund collects dividends from its underlying holdings and distributes them to shareholders, typically on a quarterly schedule.
A few more things worth knowing
Largely, yes. Selling an ETF for a gain triggers capital gains tax similar to selling a stock, and the rate depends on how long you held it. ETFs are also generally structured to be tax-efficient compared to traditional mutual funds.
Not necessarily. Some ETFs track broad indexes with hundreds of holdings, while others focus narrowly on a single sector or even a small handful of companies. Check what an ETF actually holds before assuming it’s automatically diversified.
Many brokerages now support fractional shares for both ETFs and individual stocks, letting you invest a specific dollar amount rather than needing to afford a full share.