Zero-Based Budgeting Explained
Zero-based budgeting gives every single dollar a job before the month even starts. Income minus expenses minus savings should land at exactly zero. Not because you spent it all carelessly, but because you planned every bit of it on purpose.
Zero-Based Budgeting, in Plain Terms
Zero-based budgeting means every dollar of income gets assigned a specific job before you spend a cent. Rent, groceries, savings, debt payments, even a coffee budget. Every category gets a number. Add them all up, and they should equal your total income exactly. Nothing gets left unassigned.
This is different from just tracking spending after the fact. It’s different from a general guideline like “spend less than you earn.” Zero-based budgeting forces a decision about every dollar in advance, not a reaction to where the money went once the month is already over.
The Core Rule Behind Zero-Based Budgeting
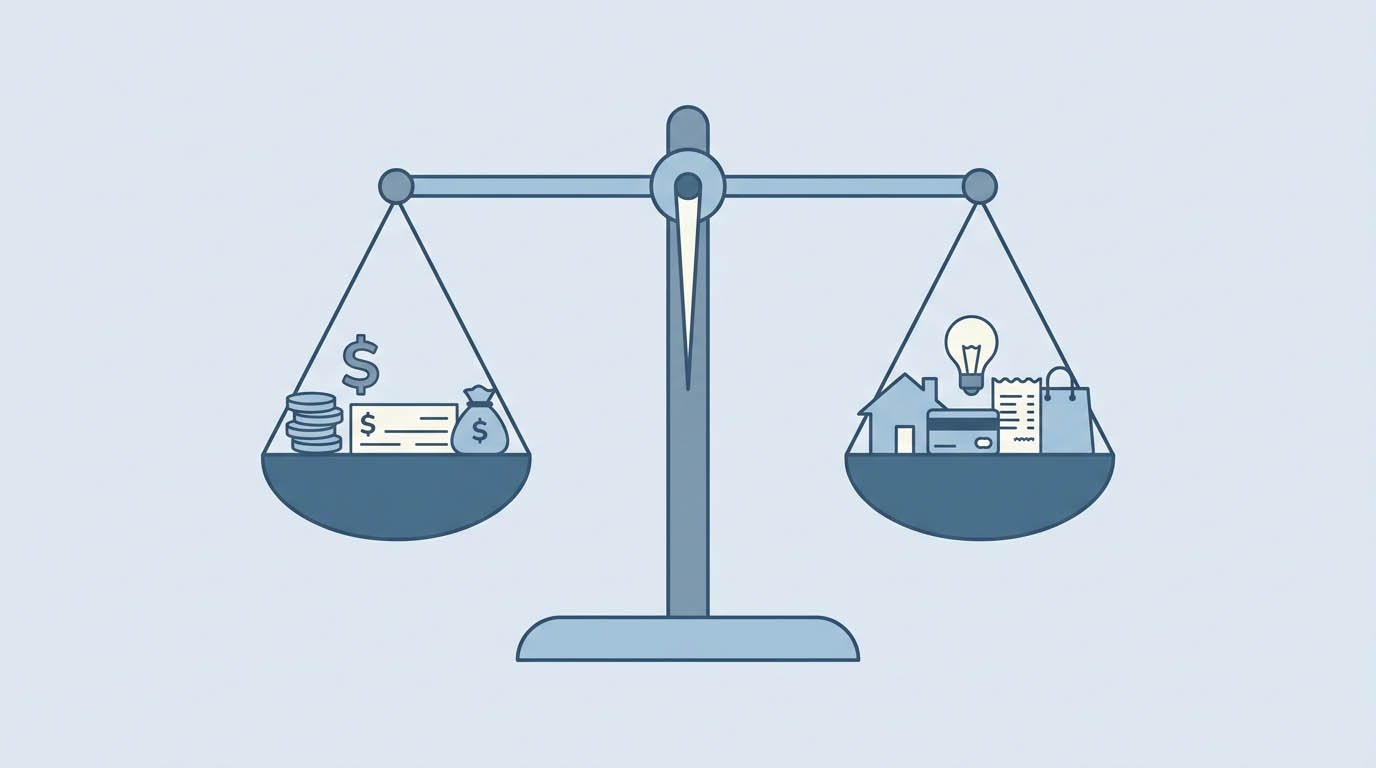
Here’s the math that gives this method its name. Take your monthly income. Subtract every expense category, including savings and debt payments. The result should be zero. Not negative, and not sitting with $400 unaccounted for either.
That leftover $400 isn’t a bad thing by itself. The problem is leaving it unassigned. Zero-based budgeting doesn’t mean spending everything. It means deciding on purpose where every dollar goes, even the $400. Maybe it goes to savings. Maybe it goes toward extra debt payoff. Either way, it gets a job instead of floating around waiting to get spent on whatever shows up first.
How This Differs From the 50/30/20 Rule
The 50/30/20 rule sorts spending into three broad buckets: needs, wants, and savings. It’s simple, and it works well as a starting framework. Zero-based budgeting goes further. Instead of three broad categories, it breaks spending into dozens of specific line items, each with its own assigned dollar amount.
Our article on the 50/30/20 budget rule covers that simpler approach in detail. Zero-based budgeting takes more effort to set up and maintain, but it gives you a far more precise picture of exactly where your money goes, category by category, rather than three general buckets that can hide a lot of detail inside them.
Step-by-Step: Building Your First Zero-Based Budget
Start by listing your total monthly income after taxes. If your income varies month to month, use a conservative recent average rather than your best month. Next, list every expense category you can think of. Rent or mortgage. Utilities. Groceries. Transportation. Insurance. Subscriptions. Debt payments. Savings goals. Even irregular categories like gifts or car maintenance deserve their own line, spread out as a monthly average.
Assign a dollar amount to each category. Add everything up. Compare that total to your income. If the numbers don’t match, adjust categories until they do. This usually means trimming a few categories down, or moving unassigned money into savings or debt payoff until the two numbers land on the exact same figure.
A Concrete Example
Say you bring home $4,200 a month after taxes. A zero-based budget might look like this: $1,300 for rent, $150 for utilities, $500 for groceries, $300 for transportation, $200 for insurance, $150 for subscriptions and entertainment, $400 for debt payments, and $600 for savings. Add those up, and you get $3,600.
That leaves $600 unaccounted for. Under zero-based budgeting, that $600 doesn’t just sit there. You assign it somewhere specific. Maybe $400 goes to an emergency fund and $200 goes to a vacation fund. Once every dollar has a destination, income minus all assigned categories equals exactly zero. Nothing is left to accidentally disappear on impulse purchases you don’t remember making.
What Happens With Irregular Income
Zero-based budgeting gets trickier with income that changes month to month, like freelance work or commission-based pay. The usual fix is budgeting based on your lowest reliable income month, then treating anything earned above that baseline as a bonus to assign once it actually arrives.
This approach keeps your baseline budget stable even during a slow month, since it was built around the worst realistic case rather than an optimistic average. Extra income in a good month gets its own zero-based treatment too, assigned to specific goals rather than absorbed into general spending without a plan.
Some freelancers keep a separate “income smoothing” account for this purpose. Deposit every paycheck into that account first, then pay yourself a fixed, budgeted amount from it each month, regardless of how much came in that particular week. This turns unpredictable income into something that behaves like a steady paycheck for budgeting purposes, even though the actual cash flow underneath stays lumpy.
Handling Expenses That Don’t Happen Every Month
Car registration, holiday gifts, an annual insurance premium, a biannual dentist visit. These costs don’t show up every month, but they’re real and predictable if you plan ahead. Zero-based budgeting handles this by dividing the annual cost by 12 and setting aside that monthly amount in a dedicated category, even in months when nothing actually gets spent.
Skip this step, and these expenses tend to blow up an otherwise careful budget the month they finally hit. Building them in as a steady monthly line item, sometimes called a sinking fund, keeps the whole system from breaking every time a predictable but infrequent bill arrives.
Reviewing and Adjusting Each Month
A zero-based budget isn’t something you build once and forget. Rebuild it at the start of each month, comparing what you planned against what actually happened the month before. Some categories will need small adjustments. A grocery budget that ran short two months in a row probably needs a higher number, not more willpower.
This monthly check-in is what keeps zero-based budgeting accurate over time. Skip it, and the plan slowly drifts away from your real spending patterns, until the whole system feels disconnected from reality and gets abandoned.
Common Mistakes That Break a Zero-Based Budget
The most common mistake is being too optimistic about spending categories, setting a grocery budget that never actually holds up in practice. This leads to constantly reshuffling money between categories, which defeats the purpose of planning ahead in the first place. Base your categories on actual past spending, not aspirational numbers you wish were true.
Another common mistake is forgetting irregular expenses entirely, then getting blindsided every few months by a bill that should have been anticipated. A third mistake is abandoning the whole system after one bad month, rather than simply adjusting the categories and trying again. Zero-based budgeting is a living plan, not a one-time exercise you set up once and never touch again.
Who Zero-Based Budgeting Actually Fits Best
Zero-based budgeting suits people who want precise control over their spending, or who are working aggressively toward a specific goal, like paying off debt or saving for a house. The extra detail pays off when every dollar genuinely needs a purpose.
People with simple, stable finances and no urgent savings goals sometimes find the detailed tracking more effort than it’s worth. A simpler framework like the 50/30/20 rule fits their situation just as well with far less monthly maintenance. Neither approach is universally correct. The right one depends on how much precision your specific financial situation actually calls for.
It’s also worth considering how much time you’re realistically willing to spend maintaining a budget each month. Zero-based budgeting rewards consistency. Set it up once and abandon it after a few weeks, and you lose most of the benefit without gaining the simplicity of a lighter-touch method either. Committing to at least a few months of consistent tracking gives the method a fair chance to prove whether it fits your habits.
Running Your Own Numbers
If you’re building out a zero-based budget and want to see how your take-home pay breaks down before you start assigning categories, our Take-Home Pay Calculator can show you your actual after-tax income to budget against. If part of your zero-based plan includes an emergency fund category, our article on building an emergency fund covers how much to actually set aside and how fast to build it.
And if debt payoff is one of your assigned categories, our Debt Payoff Calculator can help you figure out exactly how much to allocate each month to hit a specific payoff timeline.
Common questions about zero-based budgeting
No. It means every dollar, including any leftover amount, gets assigned to a specific category, like savings or debt payoff. The “zero” refers to nothing being left unassigned, not nothing being left to spend or save.
Most people rebuild their budget at the start of each month, since actual expenses and income can shift slightly from one month to the next. Some categories stay consistent, while others need adjusting based on what actually happened the prior month.
They’re related but not identical. Cash envelope budgeting is one specific method for enforcing a zero-based budget, using physical cash divided into envelopes per category. Zero-based budgeting itself can be done digitally, with a spreadsheet, or with a budgeting app instead.
A few more things worth knowing
Move money from another category to cover the overspend, keeping the overall total at zero. This is normal and doesn’t mean the system failed, it just means one category needed adjusting mid-month.
Yes, though it takes extra planning. Budgeting off your lowest reliable income month, then assigning any extra income above that baseline once it actually arrives, is the common approach for irregular earners.
No. A simple spreadsheet works fine, and several budgeting apps are built specifically around the zero-based method if you’d prefer automated tracking over manual entry.