How Much of Your Income Should You Save?
There’s no single correct percentage that fits every paycheck. But there are real anchors worth knowing: a national average, a popular rule of thumb, and a retirement-specific target that shows up in almost every financial plan. Together they give you a starting point instead of a guess.
The national average isn’t a target
The U.S. Bureau of Economic Analysis tracks something called the personal saving rate. It’s the share of after-tax income households save, rather than spend. This number is a useful economic indicator. It’s a poor personal benchmark. In late 2025, the rate sat in the mid-3% range. That’s well below what most financial planners recommend for a household trying to build real security.
That gap matters. An average pulled from every household in the country includes people with no ability to save at all in a given month. It tells you something about the economy as a whole. It tells you very little about what you, specifically, should be setting aside. Aiming for the national average means aiming low.
The 20% starting point
Most financial planners land somewhere around 20% of after-tax income as a general target for total savings. That figure combines short-term savings, retirement contributions, and any other money set aside rather than spent. One popular framework for getting there is the 50/30/20 rule. Fifty percent of income goes toward needs. Thirty percent goes toward wants. Twenty percent goes toward savings and debt paydown.
Treat that 20% as a starting anchor, not a strict law. Someone with high fixed costs in an expensive city may need a few years to work up to it. Someone with a paid-off house and grown kids might comfortably save well past it. The number gives you a place to aim. It also gives you a way to notice when you’re falling short by a lot rather than a little.
Splitting the 20%: what comes first
Where that 20% goes matters as much as the percentage itself. Most planners suggest a rough order of operations. First, build a starter emergency fund, even a small one, before anything else. Our emergency fund guide walks through getting that first cushion in place. Our sinking fund vs emergency fund article covers the difference between saving for true emergencies and saving for expenses you can already see coming.
Second, capture any employer retirement match available to you. That match is money you’d otherwise leave on the table. It typically outperforms any other move you could make with that same dollar. Third, keep building the emergency fund toward a fuller three to six months of essential expenses. From there, additional retirement contributions and other goals fill out the rest of the 20%. A house down payment, a car replacement fund, and extra debt paydown all compete for that remaining space.
Here’s how that split might look for someone earning $60,000 a year, or $5,000 a month, aiming for the full 20%, or $1,000 monthly. A starter emergency fund of $1,000 might take just one month of focused saving. Capturing a 4% employer 401(k) match costs nothing extra beyond the contribution itself, since the match is free money layered on top. The remaining $800 or so a month could split between building the emergency fund toward three months of expenses and adding to retirement accounts, with the exact ratio shifting as each goal gets closer to fully funded. Once the emergency fund reaches its target, that freed-up portion typically shifts entirely toward retirement, a taxable brokerage account, or whatever the next goal on the list happens to be.
Why retirement gets its own target
Within that overall 20%, retirement savings usually gets a specific sub-target of its own. That target is roughly 15% of income, including any employer match, saved consistently from your first working years through retirement. This number comes from modeling how much a typical earner needs to replace a reasonable share of their income later in life. It assumes decades of compounding growth along the way.
Fifteen percent starting in your twenties looks very different from 15% starting in your forties, because compounding needs time to do its work. Starting later doesn’t mean the target changes. It usually means the percentage needs to climb higher, to make up for the years already gone. Our 401(k) Calculator and Retirement Calculator both let you test what a given savings rate turns into by the time you actually need it.
Income level changes the math
A flat 20% doesn’t land the same way for every income level. Someone earning near minimum wage may spend nearly all of it on needs. That leaves little room for a 20% savings rate, no matter how carefully they budget. Someone earning well above their area’s cost of living has more room to push past 20%. They arguably should, since the marginal dollar matters less to daily life the higher income climbs.
This is part of why the 50/30/20 split works better as a guideline than a rule. Say your needs genuinely eat up 65% of your income right now. The honest move is closing that gap over time, through income growth, lower fixed costs, or both. Pretending a 20% savings rate is available today, when it clearly isn’t, just sets up a plan that fails within a few months.
A quick example: two households, two paths
Picture two single earners. One makes $45,000 a year. The other makes $90,000. Both live in the same mid-sized city, where rent for a modest one-bedroom runs about $1,400 a month.
For the first earner, that rent alone eats up roughly 37% of take-home pay before anything else gets paid. Add groceries, utilities, transportation, and insurance, and needs can easily reach 55% to 60% of income. A 20% savings rate is tight but possible, mostly by keeping wants lean.
For the second earner, that same $1,400 rent is a much smaller slice of the budget, closer to 19% of take-home pay. Needs might land around 35% to 40% of income instead. That leaves considerably more breathing room, both for wants and for savings well above 20%, without the same tradeoffs the first earner has to make.
Same city, same rent, same rule of thumb. Very different amount of effort required to hit it. This is exactly why comparing your own savings rate to a friend’s, or to a generic online benchmark, rarely tells the full story without knowing the income and cost-of-living details behind it.
Age-based benchmarks add another data point
Savings rate is only half the picture. The other half is how much you’ve actually accumulated, relative to typical milestones for your age. Our how much should you have saved by age 30 guide covers those benchmarks in more detail. Comparing your current trajectory against them can tell you whether your savings rate needs to increase, or whether you’re already on a reasonable track.
These benchmarks work best as a sanity check, not a source of pressure. Two people the same age can have wildly different starting points, family circumstances, and career paths. What matters more than matching a specific number at a specific age is whether your savings rate is trending in the right direction, year over year.
If 20% feels out of reach right now
Plenty of people can’t hit 20% the first year they try. That’s a normal starting point, not a failure. A more useful approach for a tight budget: start at whatever percentage is realistic today, even 5% or 10%. Commit to raising it by a percentage point or two with every raise or bonus, before lifestyle spending grows to absorb the extra income.
That gradual approach tends to work better than an aggressive plan abandoned within a few months. A savings rate you can actually sustain, even a modest one, compounds into real money over years. A savings rate you set too high, and quit on, compounds into nothing.
Make the percentage automatic
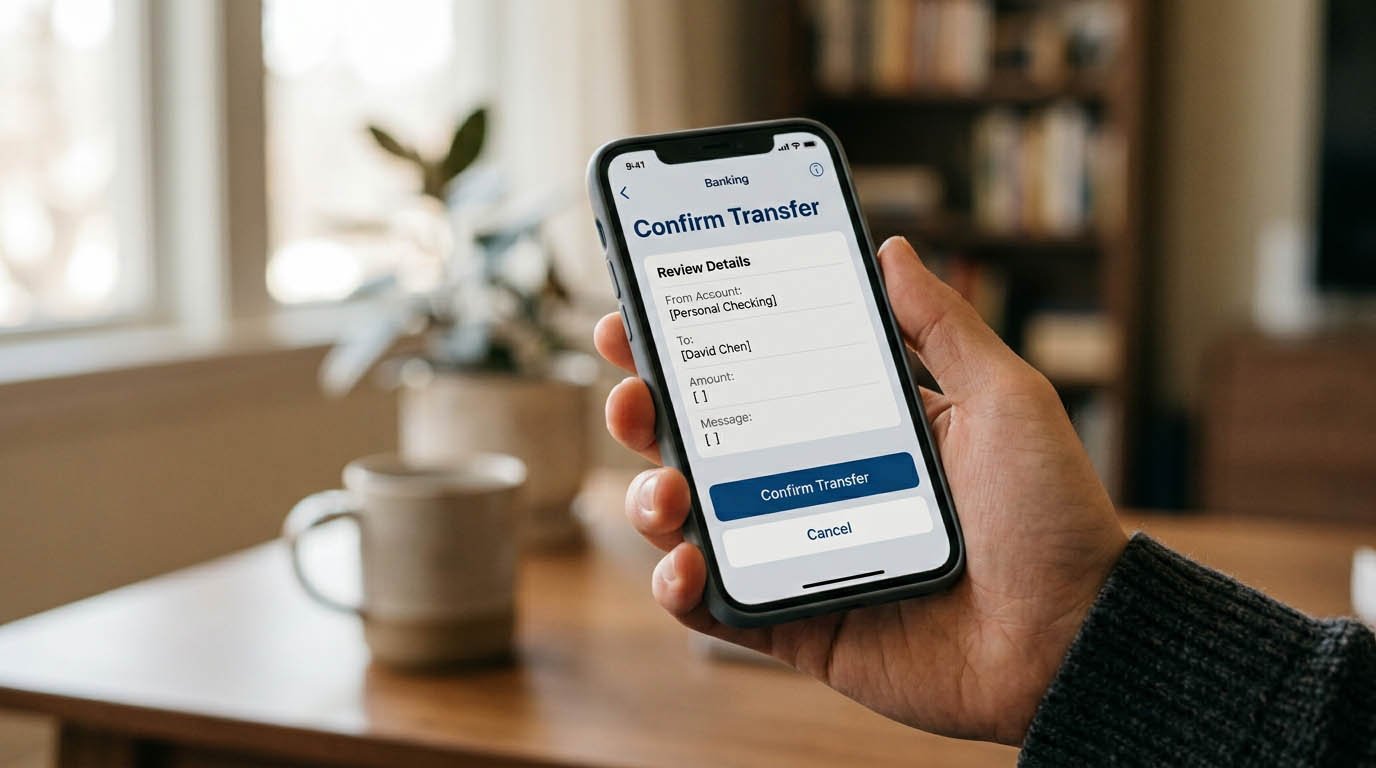
Whatever rate you land on, automation tends to matter more than willpower. Set up an automatic transfer, or split your direct deposit, so the savings portion moves out of checking before you ever see it in a spendable balance. Treat it the same way you’d treat a recurring bill.
This one change does more than any budgeting app or spreadsheet. Decisions made once, at the start of the month, tend to stick. Decisions made daily, about whether to transfer money you’re already looking at, tend to slip. Automating the transfer removes that daily decision entirely.
Revisit the percentage once or twice a year, ideally after a raise, a bonus, or a major expense finally drops off your budget. Small, periodic increases add up over a career far more than one dramatic overhaul ever does.
Check your own numbers
Our Savings Calculator shows what a given monthly savings amount grows into over time, at a chosen rate of return. It turns an abstract percentage into a concrete future dollar figure. If you want a fuller picture of where you currently stand, our Net Worth Calculator and Emergency Fund Calculator can help. Together, they show what you’ve built so far, alongside how much of a cushion you still need.
Common questions about how much to save
It’s realistic for many households, but not all, especially in high cost-of-living areas or on lower incomes. Treat 20% as a target to work toward over time, rather than a number you need to hit immediately. Even a lower rate that increases gradually beats no savings plan at all.
Yes. Most savings rate targets, including the common 20% figure, are meant to include retirement contributions, not sit separate from them. Retirement savings is simply one category within your total savings, alongside your emergency fund and other goals.
The order of priorities shifts slightly. Without a match to capture first, building your emergency fund and contributing to an IRA both become reasonable starting points. An IRA still offers tax advantages, even without an employer contribution attached.
A few more things worth knowing
Paying down high-interest debt functions like a savings return, since it’s money you’re no longer losing to interest charges. Many savings frameworks, including the 50/30/20 rule, group extra debt paydown together with savings inside that final 20% slice.
The national rate, tracked by the Bureau of Economic Analysis, reflects an average across the entire population. That average includes many households with little ability to save in a given period. It sits well below the roughly 20% figure most financial planners recommend for a household actively working toward long-term security.
Focus first on any changes, however small, that free up even $25 or $50 a month to start a habit. Don’t wait for a large surplus to feel meaningful before you begin. A tiny, consistent savings habit is easier to grow later than a large one is to start from zero.