Simple Interest vs. Compound Interest: Which Grows Faster?
Simple interest vs. compound interest: same starting amount, same rate, same number of years. One method ends thousands of dollars ahead of the other.
Simple interest vs. compound interest: the two formulas, side by side
So how does simple interest vs compound interest actually differ? Simple interest uses only the original principal, every single period, for the life of the loan or investment. The formula is about as plain as math gets: interest equals principal times rate times time. Compound interest uses the principal plus whatever interest has already accumulated. That means the base you calculate interest from grows a little bigger every period. That’s the entire difference, but it has a much bigger effect than it sounds like at first.
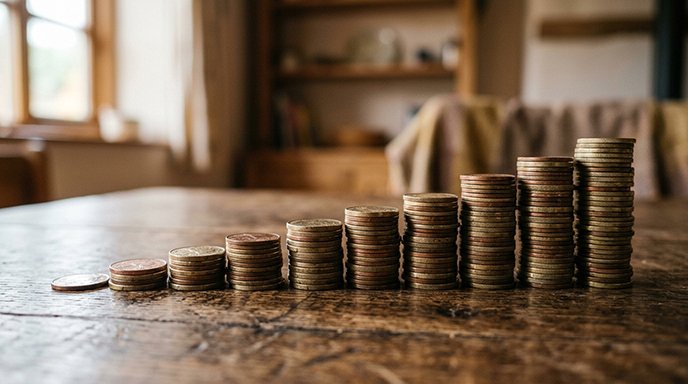
With simple interest, growth is a straight line. Double the time and the interest roughly doubles. With compound interest, growth is a curve that gets steeper the longer it runs. That’s because every bit of interest earned starts earning its own interest going forward.
The same numbers, two different outcomes
Take $8,000 at a 5% annual rate for 10 years. Under simple interest, the math is a single multiplication: $8,000 times 5% times 10 years. That comes out to $4,000 in interest, for a total of $12,000.
Run the same $8,000 at the same 5% rate for the same 10 years, but compounded monthly instead. The total comes to roughly $13,176, about $5,176 in interest, rather than $4,000. That’s over $1,100 more, generated purely because interest was accruing on a growing balance instead of a fixed one. Nothing else changed. Same money, same rate, same time.
Why the gap gets bigger over time
The 10-year example above is already a meaningful difference, but it understates how dramatic this gets over a longer horizon. Simple interest keeps adding the same fixed dollar amount every year. So a 30-year run just triples the size of the 10-year gain. Compound interest doesn’t scale that way. Each year, you calculate interest on an already-larger balance. Extending the time horizon doesn’t just add more interest. It adds interest on top of interest you already added, layered on top of interest on top of that.
This is the entire reason financial advisors talk about starting early. They treat it as nearly as important as the amount you contribute. A dollar invested at 25 has forty-plus years to compound before a typical retirement age. A dollar invested at 45 only has twenty. Under simple interest, that difference in time would matter, but proportionally. Under compound interest, it matters far more than proportionally. The extra decades aren’t just extra years of flat interest. They’re extra years for the balance itself to keep growing on top of its own growth.
Where you actually encounter each one
Compound interest is the default for almost anything built around long-term growth. Savings accounts, certificates of deposit, retirement accounts, and most investment products all compound. That’s typically daily, monthly, or annually, depending on the product. If you’re saving or investing for the future, you’re almost certainly dealing with compound interest already. That’s true whether or not the paperwork ever uses that specific phrase.
Simple interest shows up more often on the borrowing side. Think certain short-term loans, some auto loans, and a handful of bond structures. It’s also common in introductory finance education, since the math is easy enough to do by hand. That’s exactly why compound interest tends to feel like the “advanced” concept. In reality, it’s the one that shows up far more often in real financial products.
Simple interest vs. compound interest: which one is better for you
It depends entirely on which side of the transaction you’re on. If you’re saving or investing, compound interest is unambiguously better. It means your money works harder for you the longer you leave it alone. If you’re borrowing, the relationship flips. Compound interest working against you means the amount you owe can grow faster than a simple interest loan would. That’s especially true if you’re only making minimum payments. Unpaid interest joins the balance you calculate future interest on.
This is exactly why credit card debt is so much more dangerous than it initially looks. Credit cards compound, usually daily, on top of already-high interest rates. If you don’t pay a balance down aggressively, it can grow substantially, even if you technically keep making payments every month. That’s because a large share of each payment may be going toward interest that’s compounding faster than you’re paying it off.
Compounding frequency changes the math too
Compound interest isn’t just one thing; it comes in different frequencies. The frequency itself changes the outcome, though by a smaller amount than the rate or the time horizon do. Interest that compounds daily grows slightly faster than interest that compounds monthly. Interest that compounds monthly, in turn, grows slightly faster than interest that compounds annually. That’s because more frequent compounding means the balance starts earning on its own interest sooner. Take the $8,000 example above. Moving from monthly to daily compounding, at the same 5% rate for 10 years, adds a modest amount more, typically an extra few dollars to a few tens of dollars, depending on the exact rate. That’s nowhere near as dramatic as the simple-versus-compound gap itself. But it’s still a real difference that adds up on larger balances or longer time horizons.
This is part of why banks advertise a figure called APY, or annual percentage yield, alongside the nominal interest rate on savings products. APY already factors in the compounding frequency, converting it into a single effective annual rate. That makes it possible to compare two accounts fairly, even if one compounds daily and the other compounds monthly.
A quick mental model worth keeping
If you want a rough way to picture the difference without doing the math each time, try this. Imagine two savers who each start with the same amount of money and never touch it again for 30 years. The simple-interest saver’s balance rises by the exact same dollar amount every single year, like a staircase with identical steps. The compound-interest saver’s balance rises by a slightly bigger dollar amount every year than it did the year before. It’s like a staircase where each step is a little taller than the last. Over a short run, those staircases look almost the same. Over a long run, the compounding staircase pulls dramatically ahead. That’s simply because each of its steps sat on top of a taller previous step.
Try it with your own numbers
The gap between simple and compound interest depends heavily on the rate and the time period involved. It’s worth running your own numbers rather than relying on a single example. Our Simple Interest Calculator and Compound Interest Calculator use the exact same starting figures. Plug in a real principal, rate, and time horizon into both, and see precisely how large the difference gets for your specific situation.
Common questions about simple and compound interest
The standard formula is A = P(1 + r/n)^(nt), where A is the final amount, P is the starting principal, r is the annual interest rate as a decimal, n is the number of times interest compounds per year, and t is the number of years. Adding regular contributions requires an extended version of this formula.
Almost all savings accounts, certificates of deposit, and money market accounts use compound interest, typically compounding daily or monthly. Simple interest is far less common in everyday banking products and shows up more often in certain short-term loans or bonds.
Most U.S. savings accounts compound interest daily, though some compound monthly. APY, or Annual Percentage Yield, already factors in that compounding frequency. That’s why comparing APY, rather than the nominal rate, is the fair way to compare two accounts with different compounding schedules.
Credit card interest is compound. Issuers typically calculate and add it to the balance daily. This is a significant reason why carrying a credit card balance can become expensive quickly. Unpaid interest joins the balance you calculate future interest on, on top of an already high interest rate.
You calculate simple interest as Interest = Principal × Rate × Time. It always uses only the original principal, unlike compound interest, which factors in previously earned interest too.
The gap grows with time and rate. On $8,000 at 5% for 10 years, compound interest earns roughly $1,100 more than simple interest. That gap widens substantially over longer periods like 20 or 30 years.